Older buildings
Houses and flats built decades ago and not comprehensively modernised since.
Remaining useful life report · Munich metropolitan region
Is your rental building technically and economically older than the German tax office assumes by default? A report on the remaining useful life allows you to evidence the shorter useful life – and to claim higher depreciation every year for that period.
* In the years of increased depreciation. Total depreciation stays the same; it is brought forward. Whether higher depreciation is accepted is decided by the tax office case by case.
Free explainer video · Legal status 7 October 2026
How a remaining useful life report can increase the depreciation of your rental property in Germany – the basics for private investors
In around three minutes: how building depreciation works, what a remaining useful life report can do, who it may be for and how to get one. Legal status 7 October 2026.
Who for: Private investors with rented flats or houses in Germany who want to know whether a remaining useful life report can increase their depreciation.
This short course provides general information on the remaining useful life of buildings under German tax law (legal status 7 October 2026). It is not tax or legal advice, no assistance in tax matters and replaces neither advice from a tax adviser nor a report for your property. Examples are simplified and cannot be transferred to your case. Whether and to what extent higher depreciation is accepted is decided by the tax office case by case. Higher depreciation shifts depreciation forward in time; total depreciation stays the same. No advisory or information contract is concluded through use. Statutory citations are partly abbreviated; the official German wording is authoritative.
Worked example
Example: building share €400,000, acquired in the current year, marginal tax rate 42 %. Without a report, a flat rate of 2 % depreciation per year usually applies – with an evidenced remaining useful life of 25 years it is 4 %.
Simplified model calculation; constant marginal tax rate assumed. Solidarity surcharge and church tax may fall in addition. Total depreciation stays the same: the higher depreciation is brought forward and ends after 25 years (at 2 % it would run for 50 years). If the property is sold within 10 years of acquisition, the additional depreciation increases the taxable capital gain (Sec. 23 (1) sentence 1 no. 1, (3) sentence 4 EStG). Whether and to what extent higher depreciation is accepted is decided by the tax office case by case.
Who it is for
The potential is greatest where the actual useful life is clearly below the statutory flat-rate value.
Houses and flats built decades ago and not comprehensively modernised since.
Deferred maintenance, building defects or outdated building services shorten the useful life.
Outdated floor plans, poor energy efficiency or a location where a full refurbishment does not pay off.
Private individuals and companies with rented property – owner-occupied property is not depreciated.
For newer or fully refurbished buildings the effect is usually small. We check free of charge whether a shorter remaining useful life is realistic for your property – costs only arise once you commission us.
Process
Send us the year of construction, purchase data and a few photos. We tell you without obligation whether a shorter remaining useful life is realistic and quote a fixed fee.
Personal inspection recording the condition of roof, façade, windows, building services and basement – with photo documentation.
Determination of the remaining useful life using recognised methods of the ImmoWertV or SW-RL, supplemented by the individual findings on site.
A comprehensible report, usually within 10–15 working days – for submission to the tax office by you or your tax adviser. The report is written in German.
Legal basis
For buildings held as private assets, a flat-rate depreciation of 2 % per year usually applies. If the actual useful life is shorter, depreciation may be based on it (Sec. 7 (4) sentence 2 EStG). As the owner, you must provide the evidence – the report is the basis for this.
The report is an estimation basis which the tax office and fiscal court assess freely. We do not provide tax advice – please coordinate the submission with your tax adviser.
Your expert
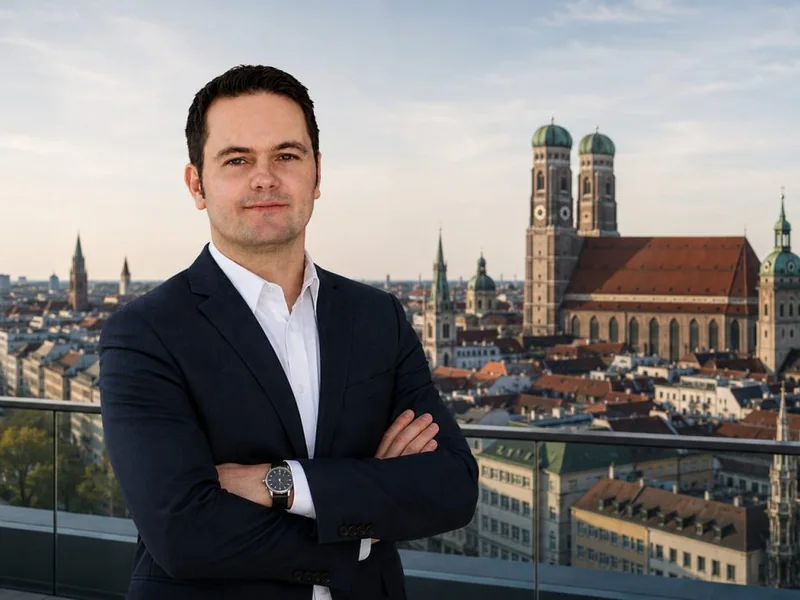
I have been valuing real estate for around 20 years – for a long time in the institutional real estate industry, today with my own valuation office for private owners, companies, banks and courts. Remaining useful life reports are one of my key areas.
More about the office: realestate-appraisal.de
FAQ
According to the Federal Fiscal Court ruling of 28 July 2021 (IX R 25/19), the taxpayer may use any method of presentation that is suitable in the individual case. The tax office assesses the report; it may review it and obtain its own counter-report. Carefully reasoned reports with an on-site inspection are regularly accepted in practice; the tax office decides on acceptance case by case.
The potential is greatest for older rented buildings that have not been comprehensively modernised, with a maintenance backlog, outdated building services or economic obsolescence. For newer, well-maintained buildings the effect is small – whether a shorter remaining useful life is realistic is what we tell you in the free pre-check.
Higher depreciation spreads the building value over fewer years: during this period your tax burden falls, afterwards depreciation ends correspondingly earlier. Total depreciation stays the same; it is brought forward. If the property is sold within ten years of acquisition, the additional depreciation increases the taxable capital gain (Sec. 23 (1) sentence 1 no. 1, (3) sentence 4 EStG). Please clarify the effect in your case with your tax adviser.
Costs depend on the property; after the pre-check you receive a binding fixed fee. For rented property, report fees are generally deductible as income-related expenses (Sec. 9 (1) sentence 1 EStG).
Usually 10 to 15 working days after the on-site inspection and receipt of the documents. The report is written in German, as it is submitted to a German tax office.
For the pre-check: year of construction, purchase date, purchase price or building share, details of modernisations and a few current photos. For the report: floor plans, purchase contract and – for condominiums – documents of the owners' association.
The report refers to a valuation date, usually the date of acquisition. Whether earlier assessments can still be amended depends on the correction rules and open tax assessments – please clarify this with your tax adviser.
The strict circular of the Federal Ministry of Finance of 22 February 2023 was revoked by circular of 1 December 2025; the law and case law are decisive again. A restriction is being discussed in the legislative procedure for the Annual Tax Act 2026 (opinion of the Bundesrat, BR-Drs. 447/26 (Beschluss) of 25 September 2026). Whether and from when it applies is open.
Send us the key data – you will receive a free, non-binding assessment and, if you are interested, a fixed fee.

Persönliches Video-Meeting per Microsoft Teams – buchen Sie jetzt Ihren Wunschtermin.

Telefonische Beratung – wählen Sie bequem Ihren Wunschtermin.

Professionelle Wertermittlung – schnell, diskret und gerichtsüblich.

Allgemeine Anfrage über unser Kontaktformular.